Commercial landscape companies are cautiously optimistic about 2027, with 45% expecting next year to be better than 2026. Meanwhile, 37% anticipate things to stay the same, according to Aspire Software’s 2027 State of Commercial Landscaping Report.
In this report, more than 1,000 commercial landscape business leaders shared their outlook for the future and what they’re doing to fuel their success. One element that showed up throughout the report was a gap between respondents’ goals and actions.
Growth Ambitions
When asked what operators are prioritizing in 2027, growing revenue (79%) far outranked increasing margins (39%).
“More revenue doesn’t automatically translate into stronger margins, especially when the cost of delivering that work is changing,” says Eli Zevin, general manager of Aspire.
Zevin adds growth only strengthens the business if operators understand what they’re spending to generate it.
“Connected systems can bring that context together and help operators act on it earlier,” Zevin says. “With a more complete picture of the business, technology and AI can surface emerging issues, identify opportunities and support better decisions about where to invest and grow. That can help operators pursue growth with a clearer understanding of what it means for the bottom line.”
While operators say they want to grow their business, an overwhelming number (63%) are still dependent on word of mouth or repeat business from existing customers. This reliance on word of mouth means landscape companies lack a repeatable, controllable way to get work beyond managing a good reputation.
Only companies $16 million and above relied less on word of mouth alone, utilizing association partnerships and outbound sales to help scale the business.
This reliance on word of mouth may be part of the reason why growth was so slow in 2025. Roughly three out of every four companies that saw any growth at all grew by 10% or less, while 17% didn’t grow at all and 24% actually declined.
Small companies were found to be the ones with the highest growth rates and the highest rate of decline.
“Smaller operators can reduce that variability as they grow by building the systems and processes that give them a clearer view of the business,” Zevin says. “Connecting estimating, job costing, scheduling, dispatching and other core workflows can help leaders understand what’s driving growth, whether that growth is profitable and where performance may be slipping.”
Yet only 23% of companies are increasing their technology and software spend next year, despite 59% saying digital transformation is very important.
Inconsistent AI Usage
This conflict in actions and beliefs is evident in companies’ current AI usage. A few years ago, most landscape companies had not even touched AI. Now, 48% of operators say they use AI in some capacity, but only 15% are using it every day.
This is despite the sentiment of operators changing from last year, when only 29% believed AI is one of the most helpful emerging technologies, to now 43% feel this way. Additionally, 52% of respondents are planning to increase their software budget for AI over the next 12 months.
Among operators using AI, most are applying it to general tasks like research (67%) and drafting content (52%), while far fewer use it for core business functions like estimating (16%) and scheduling (11%).
“Moving from general-purpose tasks into connected workflows that run the business requires operators to have greater confidence in both the technology and the value it can deliver,” Zevin says. “That’s where many are still working through challenges, with nearly half of operators citing upfront cost as a barrier, 46% say they don’t understand the technology well enough, and 29% have concerns about accuracy.”
Zevin recommends operators start with a specific business problem, whether that’s improving estimating, scheduling or another workflow, and identify where AI can make a measurable difference. Once AI has proved its value in these areas, it can build confidence and create a clearer path for expanding its usage across the business.
Increasing Material Costs
One pain point on the rise is material costs, which for the first time tied with the ever-present challenge of recruiting and retaining staff as the biggest threat to companies hitting their 2027 goals at 53%.
In fact, 85% of operators said material and equipment prices went up over the past year, and 41% said those prices went up by 10% or more. Only 8% saw no change, and just 7% saw prices go down.
Operators are no longer surprised by rising material costs, and they have also changed their purchasing habits in response. Now, 79% buy directly from the landscape supply company, up from 72% last year, in an effort to get more stable, predictable pricing.
Regionally, the South is struggling with material costs the most at 56%, while the West has the lowest concern for rising prices at 49%.
“Keeping estimates current and comparing estimated costs against actuals can help contractors account for those increases in future bids and contract renewals before they erode margins,” Zevin says.
Which Services Are Struggling the Most
Of the survey respondents, companies that do almost entirely construction work are struggling the most, with 39% seeing revenue decline, compared to 25% overall. This construction work is typically bid-build jobs (43%) versus design-build projects (34%).
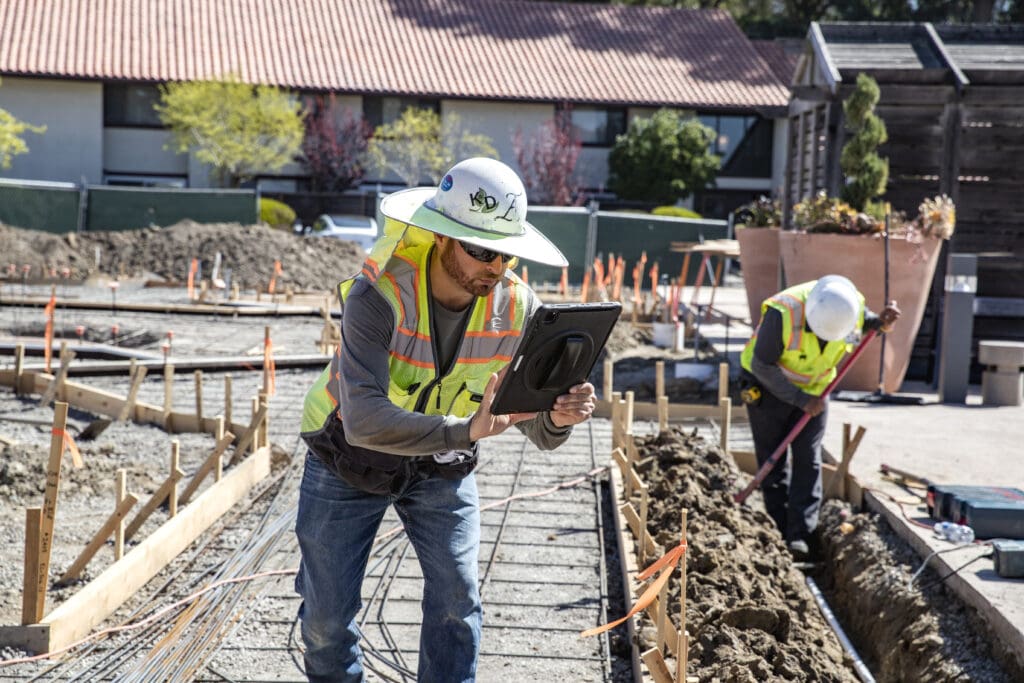
Additionally, 37% of construction companies expect 2027 to be a worse year. In response, 51% of construction companies are focused on improving their margins.
Meanwhile, landscape maintenance continues to prove to be stable. They had the lowest revenue decline rate at 21%. Most of the surveyed companies run a 75/25 split between maintenance and construction work, and 60% get more than half their total work from maintenance.
Ironically, the maintenance-heavy companies are the worst at getting paid on time, at only 31%, compared to 49% of pure-construction companies, despite 80% billing within four days.
No matter the company size or specialty, it is the implementation of better everyday processes and technology that will help operators make faster decisions about where to deploy resources, what work to pursue and how to protect profitability as the business grows.
To access the full survey report, click here.